Credit card grace period: when interest is charged (and not)
Pay the statement balance in full by the due date and purchases owe no interest. Carry a balance and you lose the grace period — the CARD Act 21-day rule.
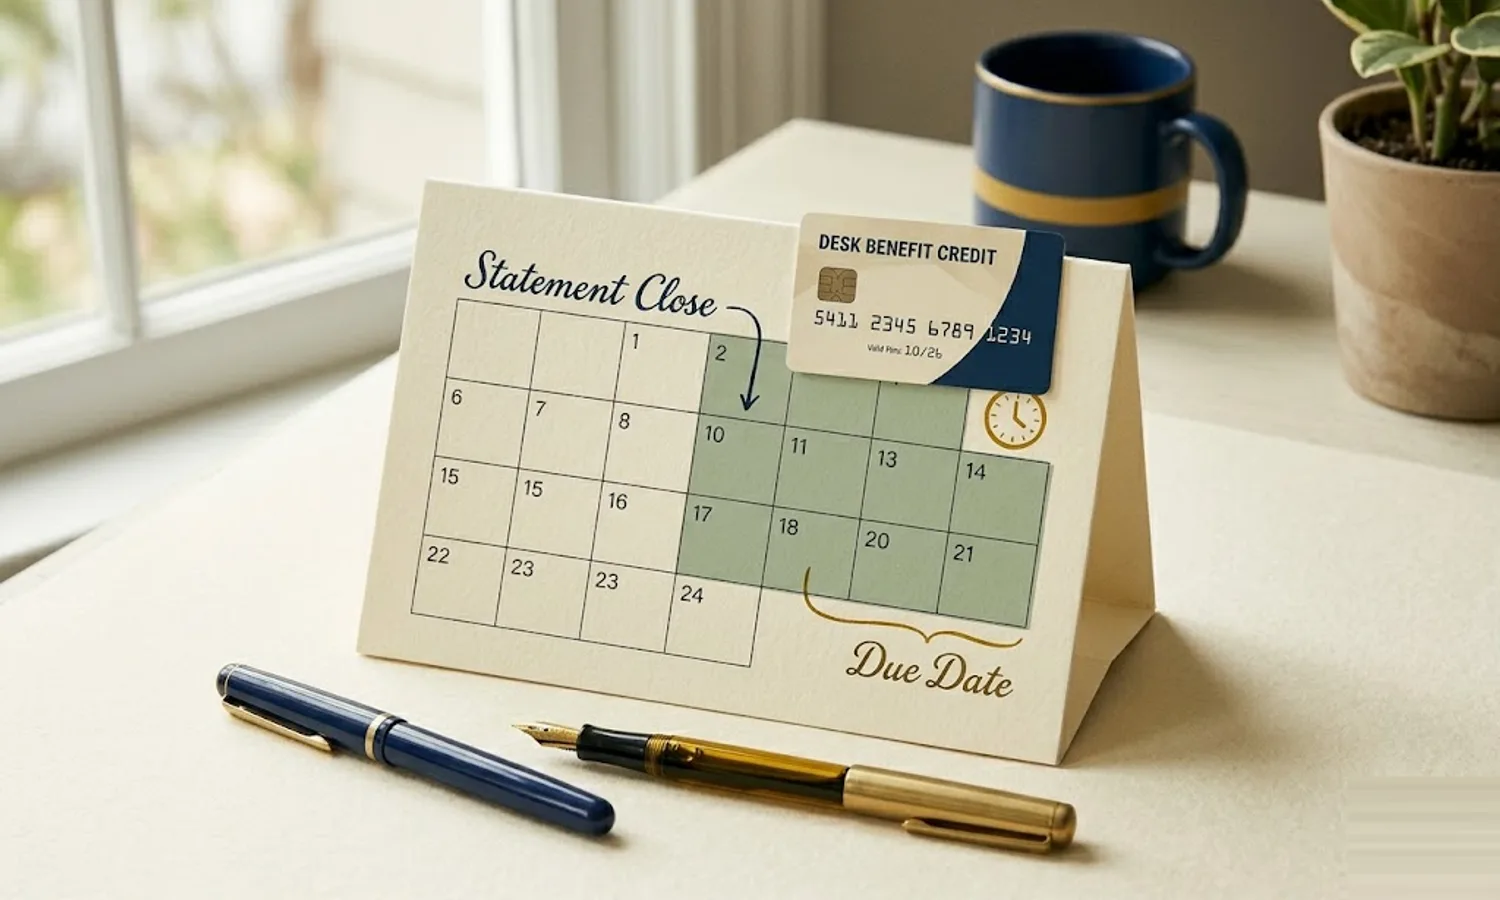
The short answer, in three rules:
- Pay the statement balance in full by the due date and purchases cost you no interest. Not the current balance, which may include purchases from the cycle that has not closed yet — the statement balance is the figure the grace period is measured against, and paying even slightly less than it forfeits the protection on the whole amount.
- Carry a balance and you lose the grace period entirely. New purchases then start accruing interest from the day you make them, with no interest-free window at all. Getting it back generally requires paying in full and staying there — at most issuers for two consecutive cycles, not one.
- Cash advances never have a grace period. Interest runs from the transaction date, on top of the advance fee, even if you pay everything off that same month — the mechanics are in cash advances and the missing grace period.
No federal law requires an issuer to offer a grace period at all. What the law does require, once one exists, is timing: under Regulation Z, 12 CFR § 1026.5(b)(2)(ii), periodic statements must be “mailed or delivered at least 21 days prior to the payment due date” and at least 21 days before the grace period expires. The regulation defines a grace period as “a period within which any credit extended may be repaid without incurring a finance charge due to a periodic interest rate” — which is why the protection covers purchases and not cash advances, where the finance charge is not the periodic rate alone.
The grace period is the single most valuable structural feature of a credit card for a borrower who pays in full each month. It is an interest-free loan from the card issuer that runs from the date of each purchase through the payment due date — typically 21 to 55 days depending on when in the billing cycle the purchase was made. A purchase made on the first day of a billing cycle receives the maximum grace period (the full billing cycle plus the 21-25 days from statement close to due date). A purchase made on the last day of the billing cycle receives the minimum grace period (just the 21-25 days from statement close to due date). In either case, no interest accrues on the purchase if the full statement balance is paid by the due date.
This interest-free window is not a default feature of credit — it is a conditional benefit that the cardholder earns by paying in full and can lose by carrying even a single dollar of balance past the due date. Most cardholders who pay in full every month take the grace period for granted without understanding the mechanics that sustain it. Most cardholders who carry a balance do not realize that the grace period has been revoked and that every new purchase is accruing interest from the moment the card is swiped. The gap between these two states — interest-free versus interest-from-day-one — is the largest financial difference between two cardholders using the exact same credit card product.
This guide covers how the grace period works under federal law, the billing cycle mechanics that determine its length, how carrying a balance eliminates it, how cash advances and balance transfers bypass it, the average daily balance calculation method that determines how much interest accrues when the grace period is lost, and the steps to restore the grace period after it has been revoked.
The short answer: A credit card grace period is the window between the statement closing date and the payment due date. Pay the statement balance in full by the due date and new purchases accrue zero interest. Carry any balance and you forfeit the grace period — interest then accrues from each transaction date until you pay in full again, typically for two cycles. The CARD Act requires at least 21 days.
What the CARD Act requires
The Credit Card Accountability Responsibility and Disclosure Act of 2009 (the CARD Act) established the federal framework for grace periods. The Act does not require issuers to offer a grace period — it requires that if an issuer chooses to offer one, it must be at least 21 days from the date the billing statement is mailed or delivered. In practice, every major US credit card issuer offers a grace period on purchase transactions, because cards without a grace period would be commercially uncompetitive.
The CARD Act also requires that the payment due date fall on the same day each month (or the next business day if it falls on a weekend or holiday), that the due date be clearly disclosed on the statement, and that payments received by 5:00 PM on the due date be treated as on-time. These protections ensure that the grace period is predictable and that cardholders are not penalized for payments that arrive on the due date rather than before it.
The key statutory language: the grace period applies to “purchase transactions” on statements where the cardholder paid the previous statement balance in full by the due date. This conditional structure — full payment of the prior balance is a prerequisite for the current cycle’s grace period — is the mechanism that connects two consecutive billing cycles and creates the “two-cycle” restoration requirement when the grace period is lost.
The billing cycle mechanics — why grace period length varies
A credit card billing cycle is typically 28-31 days (one calendar month). The cycle has a start date and a closing date. On the closing date, the issuer generates the statement, which lists all transactions from the cycle, the total balance, the minimum payment due, and the payment due date (21-25 days after the statement closing date).
The grace period for any individual purchase is the number of days from the purchase date to the payment due date. This means:
- A purchase made on the first day of the billing cycle: grace period = ~28 days (remainder of cycle) + ~23 days (statement close to due date) = ~51 days interest-free
- A purchase made on the last day of the billing cycle: grace period = ~23 days (statement close to due date) = ~23 days interest-free
- A purchase made mid-cycle: grace period = ~14 days (remaining cycle) + ~23 days = ~37 days interest-free
This variability is why strategically timing large purchases to fall early in the billing cycle maximizes the interest-free period. A $5,000 appliance purchased on the first day of the billing cycle receives nearly two months of free float; the same purchase on the last day of the cycle receives only three weeks. The billing cycle dates are visible in the card’s online portal and on every monthly statement.
How carrying a balance eliminates the grace period
The grace period is conditional on paying the full statement balance by the due date. When any portion of the statement balance is carried forward — even $1 — the grace period is revoked for the following billing cycle. The mechanical consequence is:
Cycle 1: Statement balance is $3,000. Cardholder pays $2,800 by the due date. The remaining $200 carries forward.
Cycle 2: Because the full Cycle 1 balance was not paid, the grace period is lost for Cycle 2. Every new purchase made during Cycle 2 begins accruing interest from its transaction date. The $200 carried balance also continues accruing interest. At the end of Cycle 2, the statement shows the carried balance plus new purchases plus interest accrued on both.
Cycle 3: Even if the cardholder pays the full Cycle 2 statement balance, the grace period is not yet restored. The Cycle 2 statement included purchases that accrued interest from transaction date (because the grace period was lost), and those interest charges may have generated additional balance. The grace period is restored only when two consecutive full-balance payments have been made — the first clears the carried balance, and the second clears the balance that accrued interest during the grace-period-revoked cycle.
This two-cycle restoration requirement is the mechanism that makes the grace period so easy to lose and comparatively slow to recover. A single month of carrying a balance creates a minimum of two months of interest accrual on all purchases, even if the cardholder returns to full-payment behavior immediately. The interest cost of one missed full payment is therefore not just the interest on the unpaid balance — it includes interest on every purchase made during the next billing cycle, which can be substantially larger.
Cash advances and balance transfers — no grace period applies
Cash advances never receive a grace period under any circumstance. Interest accrues from the transaction date at the cash advance APR (typically 25-30%), regardless of whether the cardholder has a grace period on purchase transactions. The CARD Act’s 21-day minimum grace period requirement applies only to purchase transactions, not to cash advances.
The definition of “cash advance” is broader than most cardholders realize. In addition to ATM withdrawals and convenience checks, many issuers classify the following as cash advances:
- Wire transfers initiated through the credit card
- Money order purchases (at the US Postal Service or retailers)
- Cryptocurrency purchases through exchanges
- Peer-to-peer payment services (some issuers code Venmo, Cash App, or Zelle transactions from credit cards as cash advances)
- Gambling transactions (online and casino)
- Some bill-pay services when the payment is not coded as a purchase
The cash advance APR and the purchase APR are disclosed separately in the card’s terms. When a cardholder has both purchase and cash advance balances, payments above the minimum are applied to the highest-APR balance first (a CARD Act requirement), which means excess payments reduce the cash advance balance before the purchase balance. This allocation rule favors the cardholder but does not eliminate the cost of the cash advance — only paying it off in full removes the daily interest accrual. For the full cost breakdown — the $10-or-5% fee, the roughly 30% APR, the transactions secretly coded as cash, and why the minimum payment never touches it — see why a cash advance has no grace period.
Balance transfers occupy a middle position. Most balance transfer offers include a promotional 0% APR period (typically 12-21 months), during which no interest accrues on the transferred balance. However, the transferred balance is not eligible for the purchase grace period — it is tracked separately and subject to its own terms. More importantly, many issuers revoke the purchase grace period on the receiving card while any promotional balance transfer balance is outstanding, meaning new purchases on the card begin accruing interest at the purchase APR from transaction date. The balance transfer mechanics guide covers this interaction in detail. The practical consequence is that a card used for a balance transfer should not also be used for new purchases until the transferred balance is fully paid.
The average daily balance method — how interest is computed
When the grace period is lost and interest accrues, the most common computation method among US issuers is the average daily balance method. The calculation works as follows:
- For each day of the billing cycle, the issuer records the balance at the end of the day (including new purchases, payments, credits, and fees posted that day).
- The daily balances are summed across all days of the billing cycle.
- The sum is divided by the number of days in the cycle to produce the average daily balance.
- The periodic rate (the annual APR divided by 365) is multiplied by the average daily balance and by the number of days in the cycle to produce the interest charge.
A worked example: a card with a 24% APR and a 30-day billing cycle, carrying $5,000 throughout:
- Daily periodic rate: 24% ÷ 365 = 0.06575% per day
- Average daily balance: $5,000 (constant throughout the cycle)
- Interest charge: $5,000 × 0.06575% × 30 = $98.63
If a $2,000 payment was made on day 15 of the cycle, the average daily balance drops: ($5,000 × 15 + $3,000 × 15) ÷ 30 = $4,000. Interest charge: $4,000 × 0.06575% × 30 = $78.90. The mid-cycle payment saved $19.73 in interest — modest, but it demonstrates why paying as early in the cycle as possible reduces interest cost, not just paying by the due date.
Promotional 0% APR and the grace period — separate mechanics
Many credit cards offer promotional 0% APR periods on purchases (typically 12-21 months after account opening) or on balance transfers. These promotional periods are structurally different from the grace period, and confusing the two is one of the most common mistakes cardholders make.
A promotional 0% APR on purchases means that no interest accrues on purchase transactions during the promotional window, regardless of whether the cardholder pays the full balance each month. This is superficially similar to the grace period, but the mechanism is different: the promotional rate suppresses interest calculation on the balance, while the grace period prevents interest from starting in the first place. The practical difference emerges at the end of the promotional period.
When the 0% promotional period ends, two things happen. First, the regular purchase APR (typically 20-28%) applies to any remaining balance from the promotional period. Second — and this is the critical point — if any balance remains from the promotional period, the cardholder has been carrying a balance, which means the grace period on new purchases was never active during that time. New purchases made after the promotional period ends (and while any promotional balance remains) accrue interest from their transaction date, not from the statement closing date. The cardholder must pay off the entire remaining promotional balance and then make two consecutive full-balance payments to restore the grace period.
Some issuers offer “deferred interest” promotional rates (common on store credit cards) rather than “waived interest” promotional rates. With deferred interest, interest accrues during the promotional period but is waived if the full balance is paid before the period ends. If any balance remains at the end, all deferred interest from the entire promotional period is charged retroactively — a mechanic that can produce hundreds or thousands of dollars in unexpected interest charges. The CFPB has repeatedly flagged deferred-interest products as a consumer-harm risk, and the disclosure requirements are stricter than for waived-interest promotions. Always confirm whether a promotional offer is “waived” or “deferred” before relying on it.
Multiple cards and the grace period — each card is independent
Each credit card in a cardholder’s wallet maintains its own independent grace period. Carrying a balance on Card A does not affect the grace period on Card B. This independence is why a common strategy for recovering from a lost grace period is to stop using the affected card for new purchases, shift daily spending to a different card that has an active grace period, and use the first card solely for paying down the carried balance.
The independence of grace periods across cards also means that a cardholder can strategically allocate spending to preserve interest-free treatment. If one card is being used for a balance transfer (which may eliminate the grace period on that card for new purchases), the cardholder should use a different card for everyday spending to maintain the grace period on those transactions. The balance transfer mechanics guide covers this allocation strategy in detail.
For households with multiple cards, the key operational discipline is simple: every card should either be paid in full each month (preserving the grace period) or not used for new purchases at all (avoiding the cost of purchasing without a grace period). Splitting the difference — making partial payments on a card while continuing to charge new purchases to it — is the worst of both worlds, because the carried balance revokes the grace period and every new purchase accrues interest from day one.
How to restore the grace period
The restoration process is mechanical: pay the full statement balance for two consecutive billing cycles. There is no shortcut, no phone call to request early restoration, and no balance threshold below which the grace period returns automatically. The two-cycle requirement exists because the first full payment clears the carried balance, and the second full payment covers the cycle during which purchases accrued interest from transaction date (because the grace period was not yet restored during that cycle).
The practical advice for a cardholder who has been carrying a balance and wants to restore the grace period:
- Stop using the card for new purchases. Every new purchase accrues interest from day one while the grace period is revoked. Switch daily spending to a different card that has an active grace period, or use a debit card temporarily.
- Pay the full statement balance on the next statement. This clears the carried balance and all accrued interest.
- Pay the full statement balance on the following statement. This second full payment covers any residual interest that accrued during the grace-period-revoked cycle. After this payment, the grace period is restored.
- Resume using the card for purchases. From the third cycle onward, new purchases will again receive the full grace period.
The cost of the two-cycle restoration is the interest accrued during the revoked cycle on purchases made before switching to a different card. For a cardholder who was spending $3,000/month on the card at 22% APR, the interest cost of one lost grace-period cycle is approximately $55-$80 — a meaningful but manageable amount that underscores why maintaining full-payment discipline every month is the most important credit card habit. The compounding psychology makes recovery harder than it appears: a cardholder who intended to pay in full next month but encounters an unexpected expense may carry a balance for a second consecutive month, extending the grace-period revocation into a third cycle and generating a cascading interest cost that grows with each month of carried balance. Autopaying the full statement balance — not the minimum, not a fixed amount, but the full statement balance — is the single most effective safeguard against accidental grace-period loss, and every major issuer offers this as an autopay option in their online portal settings.
The minimum payment trap and the grace period
The minimum payment — typically 1-2% of the balance or $25-$35, whichever is greater — is designed to keep the account current and avoid late fees and credit score damage. It is not designed to maintain the grace period. Paying the minimum when the statement balance is $3,000 means carrying $2,950-$2,975 forward, which revokes the grace period and begins the interest-accrual cycle on all new purchases.
The structural incentive for issuers is clear: a cardholder who pays the minimum is the most profitable customer. Interest accrues on the carried balance, interest accrues on new purchases (because the grace period is lost), and the minimum payment barely covers the monthly interest charge — meaning the principal balance decreases slowly while interest revenue to the issuer continues for months or years. The cardholder who pays in full each month generates transaction interchange fees for the issuer (typically 1.5-3% of each purchase) but zero interest revenue. The grace period is, in effect, the issuer’s cost of maintaining the full-payer relationship — a cost the issuer is happy to recoup the moment the cardholder carries a balance.
Sources
- CARD Act of 2009 (Credit Card Accountability Responsibility and Disclosure Act) — full text. congress.gov/bill/111th-congress/house-bill/627
- CFPB — Credit card interest rate and grace period disclosures. consumerfinance.gov/ask-cfpb/what-is-a-grace-period-for-a-credit-card-en-47
- Federal Reserve Regulation Z (Truth in Lending Act implementation) — grace period and billing cycle requirements. ecfr.gov/current/title-12/chapter-X/part-1026
- CFPB — How credit card interest is calculated (average daily balance method). consumerfinance.gov/ask-cfpb/how-is-interest-charged-on-my-credit-card-en-62
Quick answers
How long is the credit card grace period?
Federal law (the CARD Act of 2009) requires that if a credit card issuer offers a grace period, it must be at least 21 days from the date the billing statement is mailed or delivered. Most major issuers provide between 21 and 25 days. The grace period runs from the statement closing date (when the billing cycle ends and the statement is generated) to the payment due date. If the full statement balance is paid by the due date, no interest accrues on the purchases made during that billing cycle. The grace period applies only to new purchases — it does not apply to cash advances, balance transfers (in most cases), or any balance carried forward from a prior billing cycle. The exact grace period length is disclosed in each card's terms and conditions under "How to avoid paying interest on purchases."
What happens when you lose the grace period?
When you carry any unpaid balance past the payment due date, the grace period is lost — not just for the current cycle but for the next billing cycle as well. Once the grace period is lost, interest begins accruing on all new purchases from the date of each transaction, not from the statement closing date. This means every purchase you make during the next billing cycle accrues interest from day one, even if you plan to pay the upcoming statement in full. The interest charged during this period is computed using the average daily balance method, which sums the daily balances for each day of the billing cycle and divides by the number of days. To restore the grace period, you must pay the full statement balance in full for two consecutive billing cycles — the first payment clears the carried balance, and the second payment (on a balance that includes purchases that accrued interest from transaction date) restores the grace period for the third cycle onward.
Do cash advances have a grace period?
No. Cash advances — including ATM withdrawals, convenience checks, cash-equivalent transactions (money orders, wire transfers, cryptocurrency purchases at some issuers), and some payment services — begin accruing interest from the transaction date with no grace period regardless of your payment status. Even if you have never carried a balance and always pay in full, a cash advance starts accruing interest immediately. The APR for cash advances is also typically higher than the purchase APR — 25-30% versus 20-25% at most major issuers. Additionally, cash advances usually carry a transaction fee of 3-5% of the amount advanced ($10 minimum). The combination of no grace period, higher APR, and transaction fee makes cash advances one of the most expensive forms of short-term borrowing available through a credit card.
If I pay more than the minimum but less than the full balance, do I keep the grace period?
No. The grace period requires payment of the full statement balance — every dollar on the statement — by the due date. Paying more than the minimum but less than the full balance is better than paying only the minimum (the remaining balance is smaller and less interest accrues), but it does not preserve the grace period. Any unpaid portion of the statement balance means interest will accrue on all new purchases from transaction date during the next billing cycle. The only payment amount that preserves the grace period is the "statement balance" or "new balance" printed on the statement — not the "minimum payment due" and not the "current balance" (which may include transactions from the current cycle that are not yet on a statement).
When does a credit card start charging interest?
If you paid your last statement balance in full by the due date, your card charges no interest on new purchases as long as you keep paying the statement balance in full — the grace period covers them from purchase date through the due date. Interest only starts being charged when you carry a balance past the due date: once that happens, you lose the grace period, and every new purchase begins accruing interest from its transaction date (not the statement date) until you pay the balance in full again, which typically takes two consecutive full-payment cycles. Cash advances are the exception — they accrue interest from the transaction date with no grace period, even if you always pay in full.
Educational content only. finbarrow is an independent editorial publication, not a licensed financial advisor, broker, tax preparer, or attorney. Verify rates and terms with the issuer or relevant regulator. See disclaimers and funding disclosures.